Powerball Jackpot Payout Guide: Cash Value, Taxes, and Claiming Rules
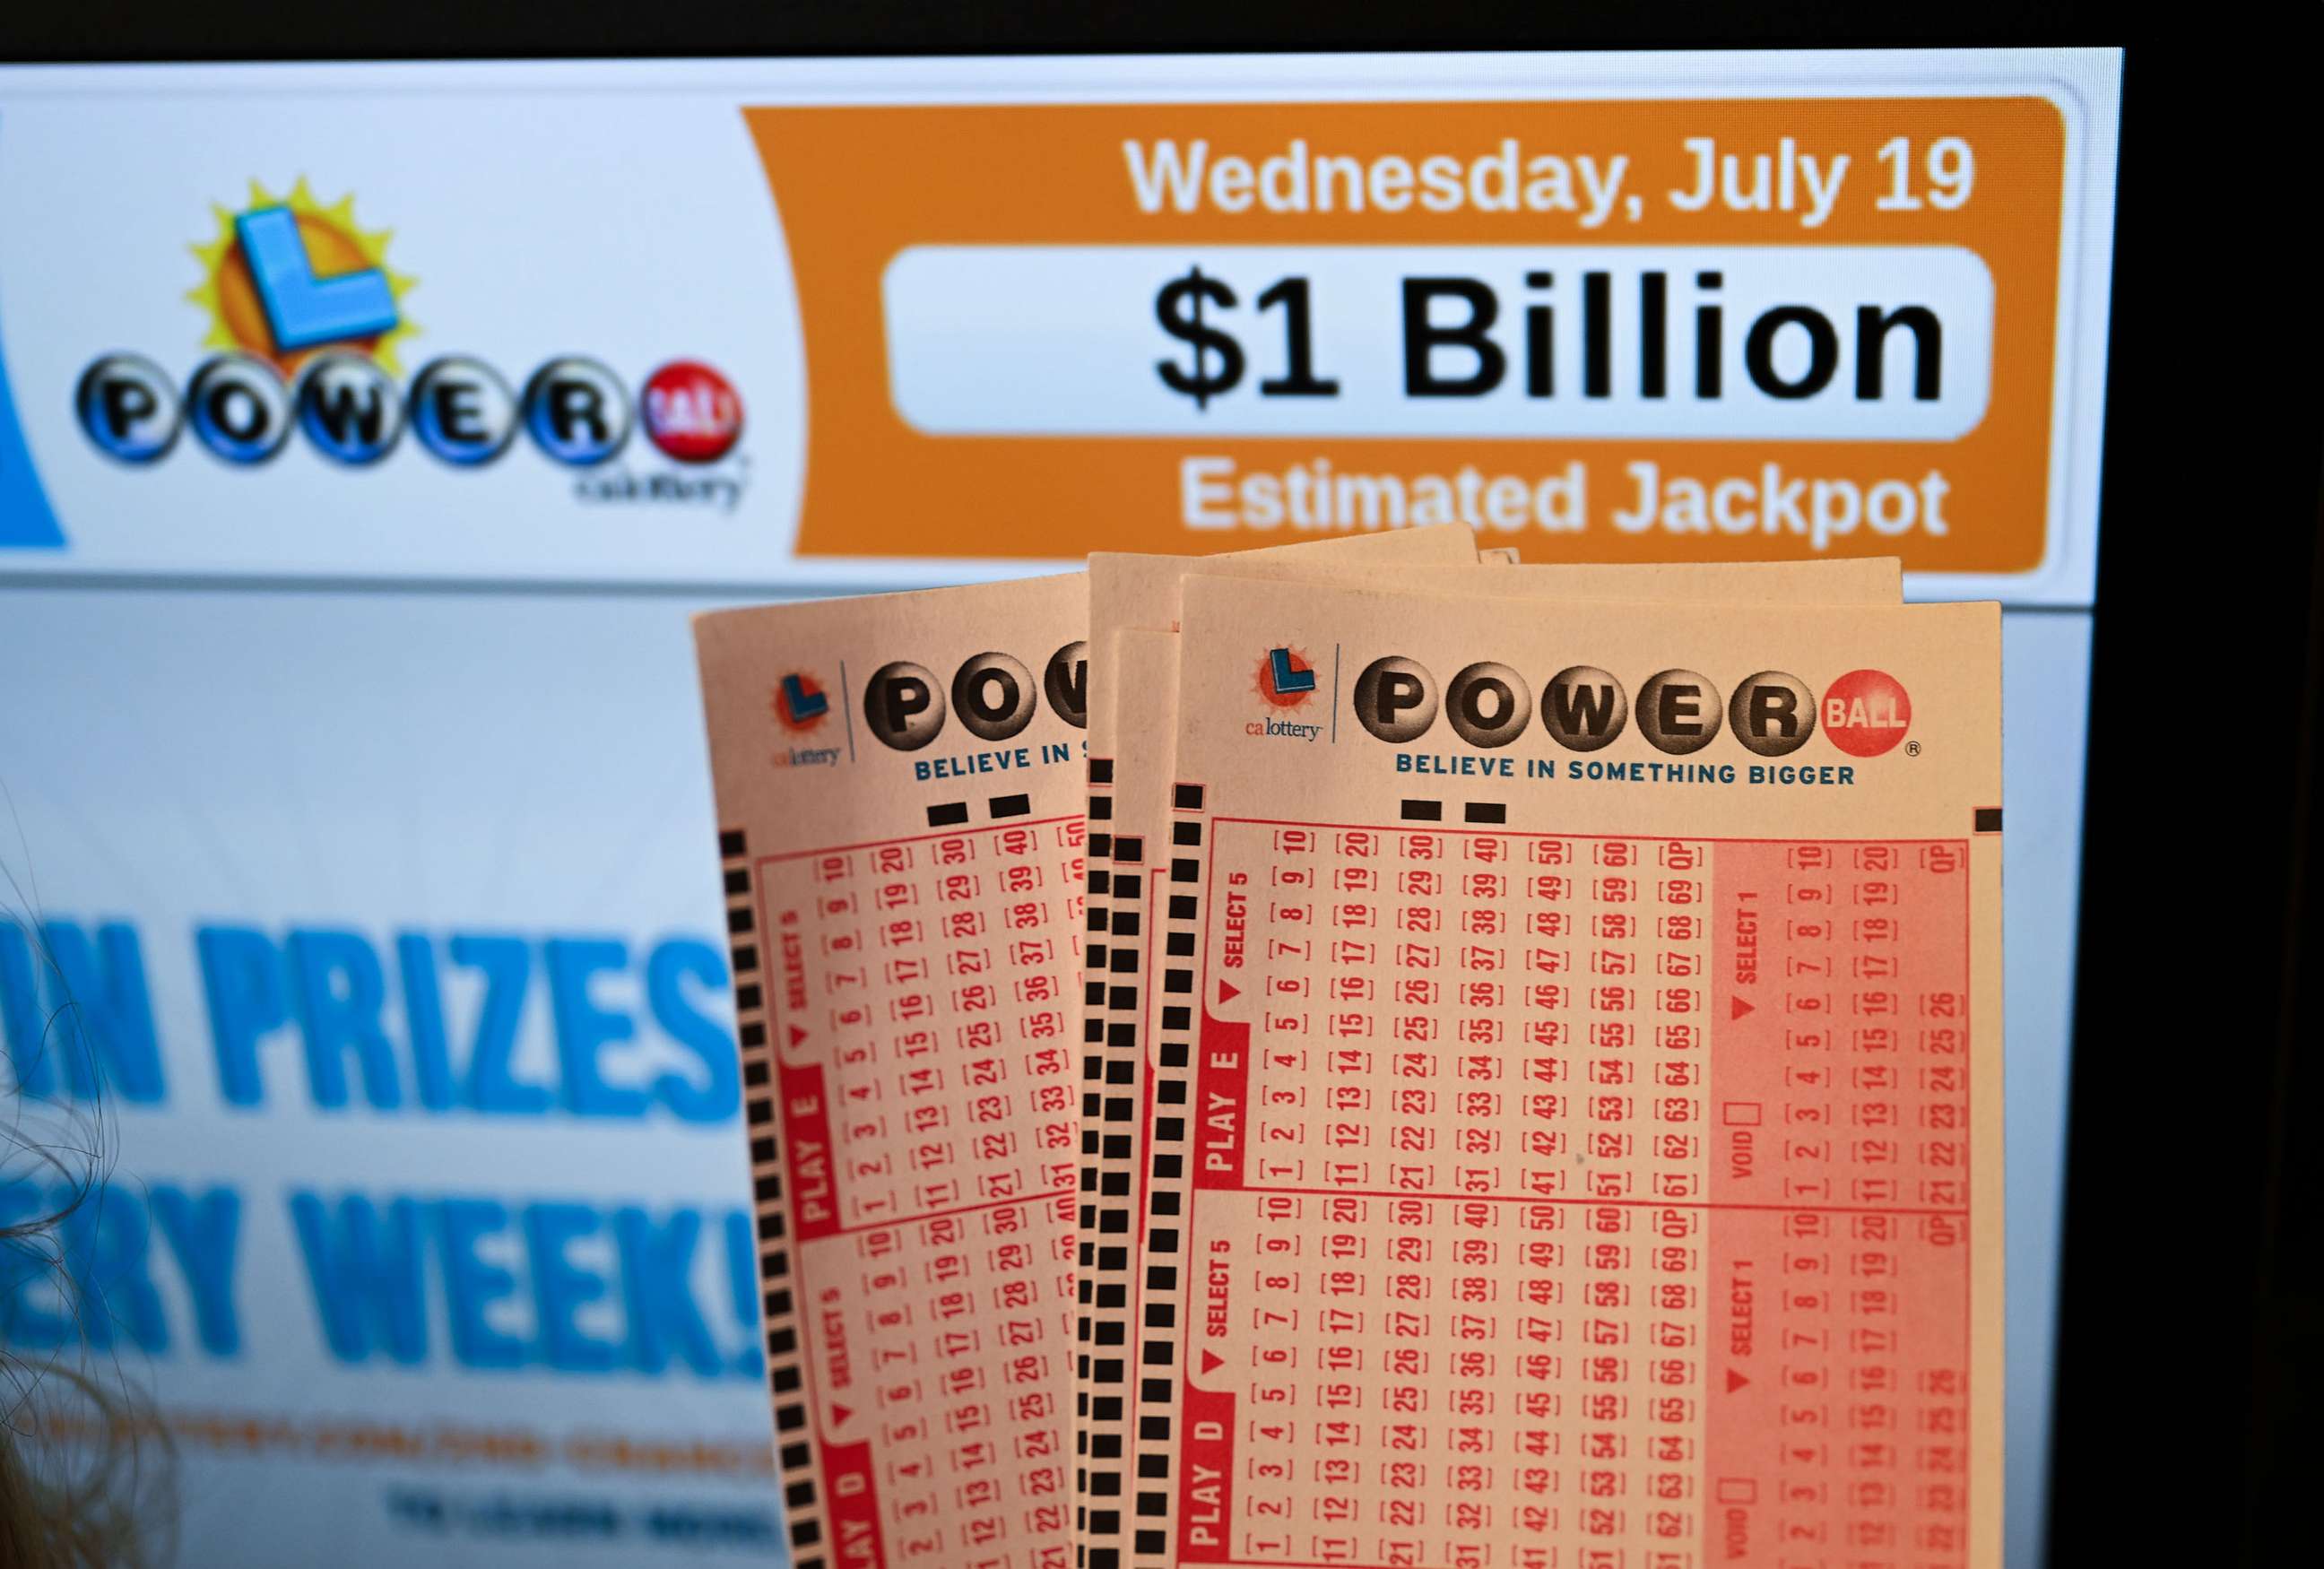
When the Multi-State Lottery Association flashes a nine- or ten-figure estimate across billboards, the public sees an astronomical fortune. In August 2026, as the grand prize crossed the $1 billion mark following consecutive rollovers, ticket counters across 45 states saw hours-long lines. Yet the gap between the headline estimate and the actual bank deposit remains one of the most misunderstood calculations in modern consumer finance. Detailed analysis from a recent MLive.com Report tracking ticket purchases and prize mechanics reveals that what an individual pockets bears little resemblance to the giant novelty check.
A winning ticket is an asset subject to immediate financial discounting, mandatory federal withholdings, state tax exposure, and legal costs. Determining what a Powerball ticket is worth requires stripping away marketing projections to examine cash value ratios, effective tax brackets, and claims governance.
📌 Key Takeaways:
- The Real Cash Value: The immediate lump-sum cash option payout typically equals 48% to 52% of the advertised annuity jackpot, determined entirely by prevailing U.S. Treasury bond yields.
- Mandatory Tax Deductions: The IRS claims an immediate mandatory 24% federal withholding at redemption, with top-tier federal income tax liability pulling the final federal tax bite to 37% the following April.
- State Impact: Net take-home amounts swing wildly by geography, ranging from 0% in states like Texas, Florida, and California to over 10.9% in New York and New Jersey.
- Strict Redemption Clocks: Claiming rules and deadlines give winners between 90 and 365 days to claim funds, depending entirely on state lottery commission rules.
How the Multi-State Lottery Association Calculates the Advertised Jackpot
The headline number promoted during every drawing cycle does not represent money sitting idle in a vault. The Multi-State Lottery Association (MUSL) derives its headline jackpot by projecting a 30-installment annuity funded by current ticket sales and invested in fixed-income securities.
When a player chooses the annuity, the lottery buys an investment portfolio of U.S. government Treasury zero-coupon bonds. The advertised jackpot represents the total pretax sum of an initial payment followed by 29 annual disbursements that increase by 5% every year to adjust for expected inflation.
When interest rates sit near modern historic averages, the bond portfolio can generate substantial compounding over three decades. Consequently, when bond yields rise, the cash value required to fund the annuity falls; conversely, lower interest rates require lotteries to assemble a much larger immediate cash pool to promise the same annuity figure. For players seeking upfront cash, that projected 30-year accumulation vanishes immediately.
Cash Option Versus Annuity: The Mechanics of the Lump Sum
The immediate choice facing every jackpot winner is binary: take the full stream across three decades or select the cash option payout.
Opting for the lump sum delivers the exact amount of cash the lottery would have used to purchase the 30-year Treasury bond portfolio. For an advertised $1 billion prize, the cash option typically settles near $475 million to $510 million.
Historically, over 95% of American grand prize winners select the immediate lump sum. Certified financial planners often support this route on the premise that an experienced wealth management team can beat conservative federal bond yields over three decades. However, accepting the upfront cash forces the entire fortune into a single tax year, generating the maximum possible tax bracket hit simultaneously on hundreds of millions of dollars. The annuity shields winners from their own behavioral impulses, offering guaranteed annual income that cannot be wiped out by sudden market crashes, failed venture investments, or predatory associates.
The Realistic Take-Home Calculation: Taxes at Federal and State Levels
Federal and state tax authorities treat lottery winnings as ordinary income, not capital gains. Before a single cent reaches a winner's checking account, the internal revenue service secures its cut directly at the state lottery office.
The lottery automatically withholds a mandatory 24% for federal taxes. Because single filers hit the maximum 37% federal income tax bracket at income levels above $609,350 (and married couples at $731,200), winners must write a supplemental check for the remaining 13% federal balance during the subsequent tax filing window.
State lottery taxes compound the reduction. Eight states, including California, Florida, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming, levy zero tax on lottery prizes. Other states, such as New York (10.9%), New Jersey (10.75%), and Maryland (8.95% for residents, 8.0% for nonresidents), take massive slices.
| Advertised Jackpot | Estimated Cash Option | Federal Tax (37% Total) | Net Payout (0% State Tax) | Net Payout (10% State Tax) |
|---|---|---|---|---|
| $200 Million | $98.2 Million | $36.3 Million | $61.9 Million | $52.1 Million |
| $500 Million | $246.5 Million | $91.2 Million | $155.3 Million | $130.6 Million |
| $1.0 Billion | $495.0 Million | $183.1 Million | $311.9 Million | $262.4 Million |
| $1.5 Billion | $740.0 Million | $273.8 Million | $466.2 Million | $392.2 Million |
A headline prize of $1 billion shrinks to roughly $262 million to $312 million in true liquidity depending on the claimant's residency. Municipal taxes in cities like New York or Philadelphia pull that realization even lower.

Ticket Economics and the Mathematical Reality of the Odds
Every Powerball ticket costs $2, with an optional $1 Power Play add-on that multiplies non-jackpot prizes. Drawings occur three times weekly, every Monday, Wednesday, and Saturday night at 10:59 p.m. Eastern Time from the Florida Lottery draw studio in Tallahassee.
The overall odds of winning any prize stand at 1 in 24.87, but those secondary prizes are modest sums ranging from $4 (for matching the red Powerball alone) to $1 million (for matching five white balls). The mathematical odds of matching all five white balls (selected from 1 to 69) and the red Powerball (selected from 1 to 26) sit unyieldingly at 1 in 292,201,338.
To grasp that probability: a buyer purchasing 100 tickets every week would statistically expect to land the grand prize once every 56,000 years. Because ticket sales surge exponentially whenever the estimated prize tops $800 million, the mathematical likelihood of split jackpots rises in tandem. If three winning tickets match the same sequence on drawing night, the lump sum cuts cleanly into three equal shares before tax calculations even start.
Strategic Protocols for Claiming a Winning Ticket
Holding a winning ticket worth hundreds of millions poses an acute security and legal liability. Lottery tickets function as bearer instruments under commercial statutes. Whoever physically holds the signed ticket legally controls the prize.
Estate attorneys and fiduciary advisors recommend a strict, sequence-based protocol before anyone approaches a state lottery headquarters:
- Sign and Secure the Physical Slip: Write full legal names and contact details on the back of the ticket immediately, photograph the front and back against that day's newspaper, and deposit the paper ticket inside a bank safe deposit box.
- Establish a Multi-Disciplinary Professional Team: Engage an estate planning attorney specializing in high-net-worth liquidity events, a CPA experienced with federal top-bracket tax mitigation, and an established fiduciary wealth advisor before initiating communications with lottery officials.
- Investigate Anonymity Statutes: Laws regarding public disclosure vary dramatically by jurisdiction. States such as Delaware, Kansas, Maryland, North Dakota, Ohio, and South Carolina allow winners to maintain complete anonymity. Other states, including California and Michigan, legally require the winner’s full name to be published as public record. In select states, attorneys can claim prizes through a blind trust or limited liability company (LLC) to protect client privacy.
- Claiming periods range from 90 days to one full year from the official drawing date depending on state regulations. Missing the operational deadline forfeits the claim entirely, returning the unclaimed funds to state educational budgets and general lottery prize pools.
Frequently Asked Questions (FAQ)
Q1: Can non-U.S. citizens win and claim the Powerball jackpot?
Yes. You do not need to be an American citizen or lawful permanent resident to purchase tickets or claim prizes. However, foreign nationals face a mandatory 30% federal withholding tax upfront instead of 24%, along with relevant state taxes and local bilateral tax treaties between the United States and their home nation.
Q2: What happens if an annuity recipient dies before 30 years?
The remaining payments do not return to the lottery system. The future installment streams transfer directly to the winner's heirs or designated estate beneficiaries according to standard probate law. An estate can also petition the lottery to liquidate the remaining bond portfolio to cover federal estate taxes.
Q3: Does buying more tickets materially improve individual winning chances?
Statistically, no. Buying 10 tickets shifts the probability from 1 in 292.2 million to 10 in 292.2 million, a change so minuscule that it remains indistinguishable from zero in statistical models. Pools and syndicates increase odds slightly by volume, but they simultaneously dilute the net payout across multiple participants.
Managing Expectations in the Era of Giant Jackpots
The massive numbers displayed on highway billboards represent a marketing projection rather than liquid personal wealth. An advertised $1 billion prize delivers an effective post-tax realization hovering near 26% to 31% of the billboard figure for most Americans. Understanding the discount mechanisms, bond yields, and tax implications converts the fantasy of multi-generational wealth into realistic mathematical facts. For those holding a ticket on drawing night, the true test begins not at the retailer terminal, but in the disciplined management of the numbers that remain after taxes.


